Pensions · Updated for 2026
FERS Retirement Calculator
Estimate your FERS pension the way OPM works it out: High-3 × multiplier × years of service, with your eligibility, MRA+10 reduction, sick leave, military buyback, survivor cost and FERS Supplement.
The short answer
Your FERS basic annuity is your High-3 average salary × 1% × your years of creditable service. It rises to 1.1% if you retire at 62 or older with 20 or more years, and unused sick leave counts toward those 20 years. Retire at your minimum retirement age with 10 to 29 years and the annuity is cut 5% for each year you are under 62.
Estimate your FERS annuity
Estimated monthly FERS annuity
$0
Per year
$0
A planning estimate using OPM's published FERS rules. It doesn't include your TSP, Social Security after 62, FEHB or FEGLI premiums, or taxes. Your agency's HR office prepares the official retirement estimate.
How is FERS retirement calculated?
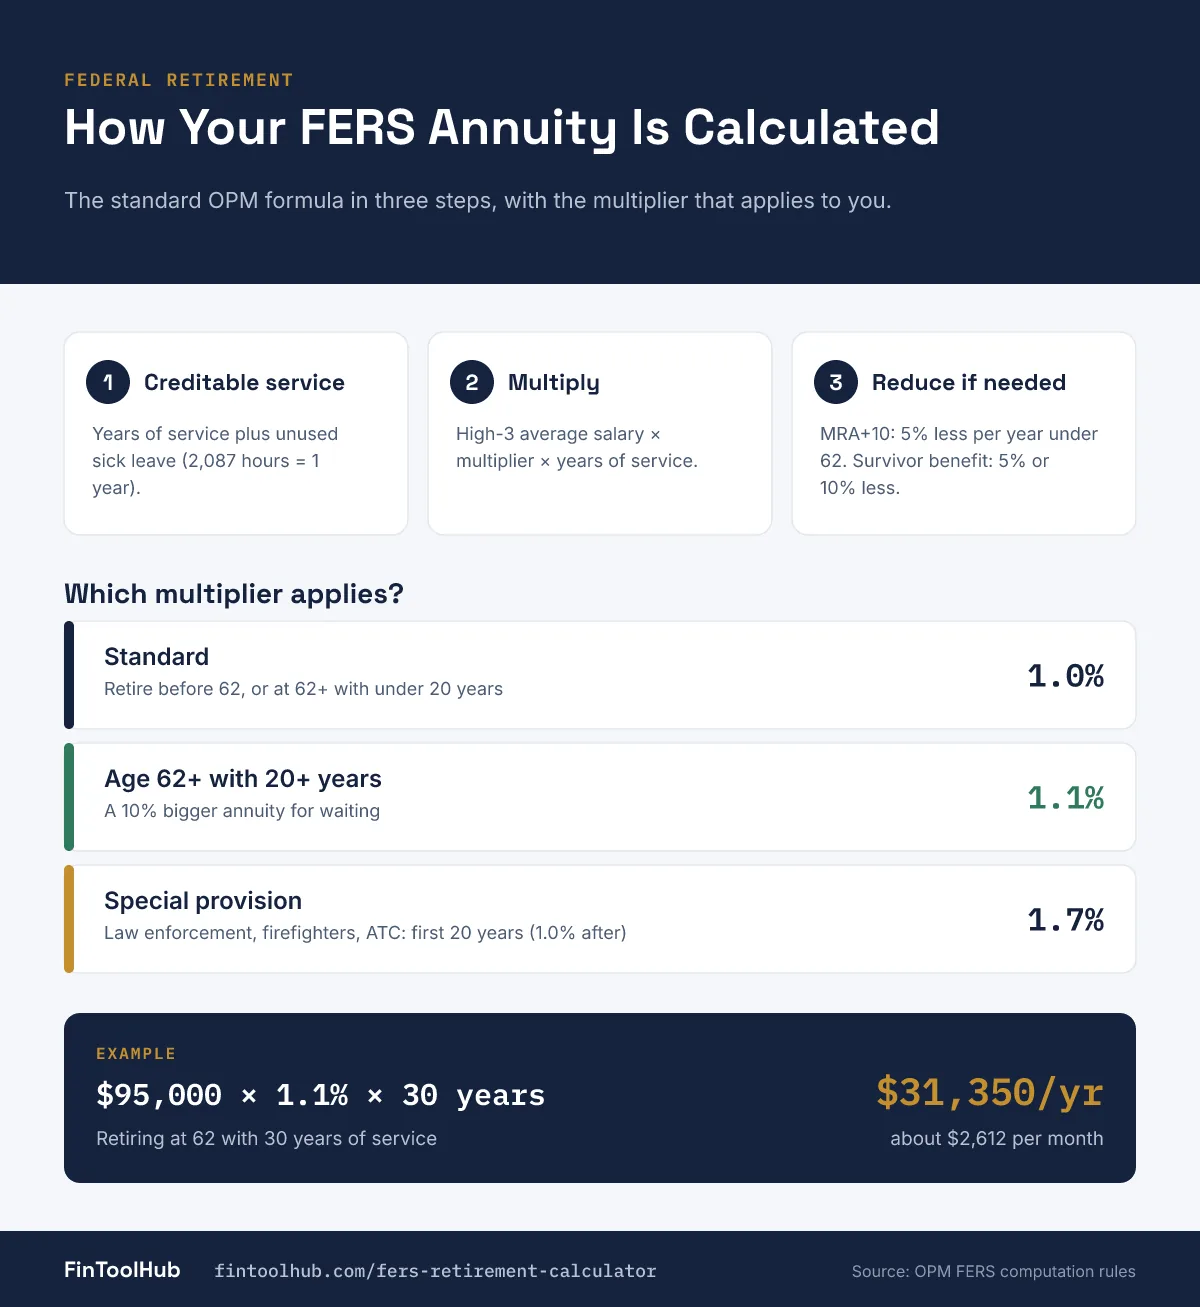
The FERS basic annuity comes from three numbers: your High-3, your years of creditable service and a multiplier.
- High-3: the highest average basic pay you earned in any three consecutive years, usually your last three. Locality pay counts. Overtime, bonuses and awards don't.
- Service: your civilian FERS service, plus military time you bought back, plus unused sick leave. OPM drops any fraction of a month from the total.
- Multiplier: 1% for most people. 1.1% if you are 62 or older when you separate and have at least 20 years. Special provision employees get 1.7% for their first 20 years.
FERS retirement calculator example
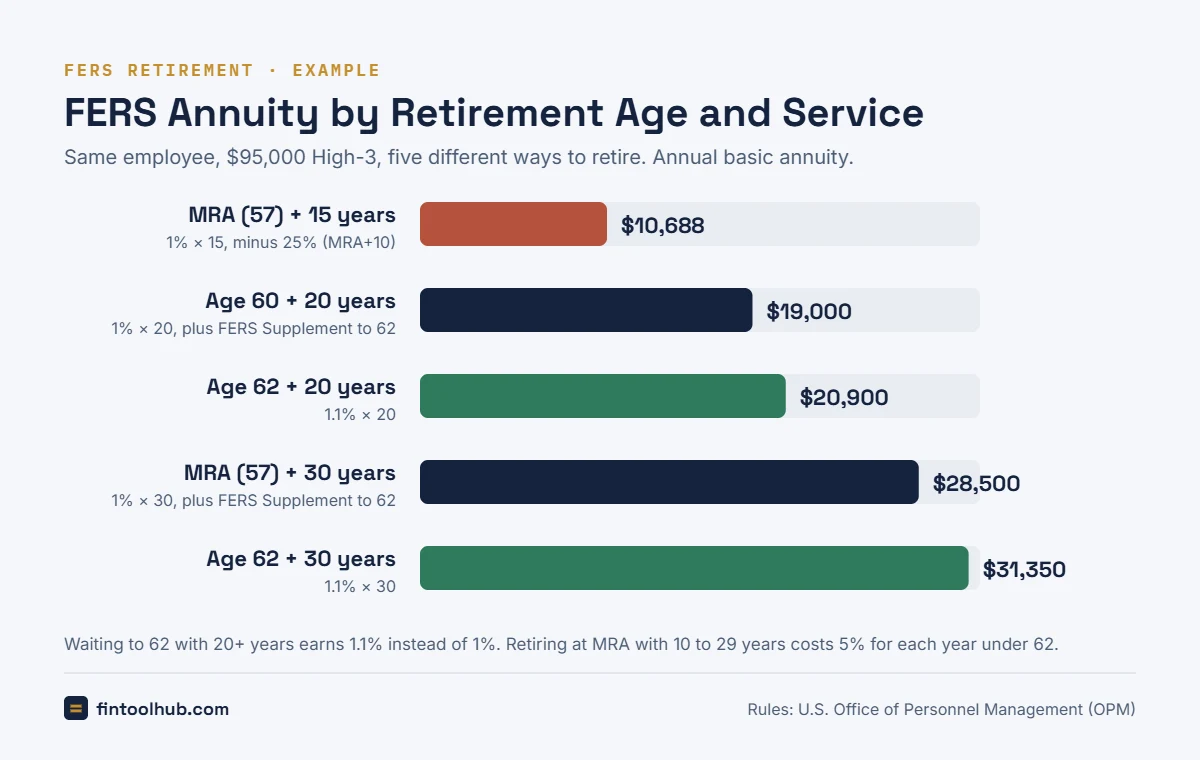
Take an employee with a $95,000 High-3. Here is what the same person gets depending on when they leave:
- At 62 with 30 years: $95,000 × 1.1% × 30 = $31,350 a year, about $2,612 a month.
- At their MRA of 57 with 30 years: $95,000 × 1% × 30 = $28,500 a year, plus the FERS Supplement until 62.
- At 57 with 15 years (MRA+10): $95,000 × 1% × 15 = $14,250, cut by 25% for being five years under 62, so $10,688 a year.
The difference between the best and worst of those is almost $21,000 a year, for the rest of your life. That is why the date you pick matters as much as your salary.
When can I retire under FERS?
You can take an immediate, unreduced annuity at any of these points:
| Age | Years of service | Annuity |
|---|---|---|
| 62 | 5 | Full |
| 60 | 20 | Full, plus FERS Supplement to 62 |
| MRA | 30 | Full, plus FERS Supplement to 62 |
| MRA | 10 to 29 | Reduced 5% a year under 62 (MRA+10) |
Your minimum retirement age depends on the year you were born:
| Year of birth | MRA |
|---|---|
| Before 1948 | 55 |
| 1948 to 1952 | 55 plus 2 months per year after 1947 |
| 1953 to 1964 | 56 |
| 1965 | 56 and 2 months |
| 1966 | 56 and 4 months |
| 1967 | 56 and 6 months |
| 1968 | 56 and 8 months |
| 1969 | 56 and 10 months |
| 1970 and later | 57 |
What is the best age to retire from federal service?
There's no single best age, but there are three dates worth circling:
- 62 with 20 or more years gets you the 1.1% multiplier: a 10% bigger annuity for life. If you're close, the extra year or two often pays for itself.
- Your MRA with 30 years, or 60 with 20 years, gets you an unreduced annuity plus the FERS Supplement, which bridges the gap until Social Security at 62.
- Avoid MRA+10 if you can. If you need to leave early, consider postponing the annuity start (see below) rather than taking a 25% cut for life.
Two practical checks before you pick a date: you need to have been in FEHB for the five years right before you retire to keep your health insurance, and your annuity starts the first day of the month after you separate, so many people time their last day for the end of a month.
The MRA+10 reduction, and how to avoid it
If you retire at your MRA with 10 to 29 years, OPM reduces your annuity by 5/12 of 1% for each full month you are under 62, which is 5% a year. Retire at 57 and that's a 25% cut that never goes away.
You can avoid it by postponing your annuity. Leave at your MRA, then start the annuity later: with 20 or more years, no reduction applies if it starts at 60 or later; with 10 to 19 years, start it at 62. Set the calculator's annuity start date to compare.
How unused sick leave increases your FERS annuity
Every 2,087 hours of unused sick leave adds one year of service to your annuity computation. FERS employees who retired on or after January 1, 2014 get credit for 100% of their sick leave.
- It counts toward the annuity formula, and toward the 20 years you need for the 1.1% multiplier at 62. OPM confirmed this in benefits letter BAL 18-103.
- It does not count toward eligibility to retire, and it doesn't change your High-3.
Example: 1,040 hours is about half a year. On a $95,000 High-3 at 1%, that's roughly $475 more a year, every year.
Adding military service
Post-1956 military service can count toward your FERS annuity if you make a military deposit of 3% of your military basic pay (with interest after the first two years). The deposit has to be paid to your agency before you retire. Once it is, that service counts toward both eligibility and the annuity. If you receive military retired pay, you generally have to waive it for the service to count. Enter the years in the calculator's military field.
Law enforcement, firefighters and air traffic controllers
Special provision employees can retire at 50 with 20 years of covered service, or at any age with 25 years, with no reduction. Their annuity uses 1.7% for the first 20 years and 1% for each year after that. A law enforcement officer with a $100,000 High-3 and 25 years gets $100,000 × (34% + 5%) = $39,000 a year. They also get the FERS Supplement, and face a mandatory retirement age, generally 57.
The FERS Supplement
If you retire before 62 on an immediate, unreduced annuity (MRA+30, 60+20 or special provision), OPM adds a supplement that stands in for the Social Security you earned as a federal employee until you can claim the real thing.
With 30 years and an $1,800 Social Security estimate, that's $1,800 × 30/40 = $1,350 a month. It stops at 62, doesn't get cost-of-living increases, and is reduced if you earn above the Social Security earnings limit. MRA+10 and deferred retirees don't get it.
Survivor benefits: what they cost
A full survivor benefit (50% of your annuity for your spouse after you die) costs 10% of your annuity. A partial one (25%) costs 5%. If you're married, your spouse has to consent in writing to anything less than the full benefit. It is also usually the only way your spouse keeps FEHB coverage after your death.
Deferred retirement
Left federal service before you were eligible to retire? With at least 5 years of creditable civilian service you can still claim a deferred annuity at 62, at your MRA with 30 years, or at your MRA with 10 years (reduced 5% a year under 62). Deferred annuities use the 1% multiplier, don't include the FERS Supplement, and don't let you keep FEHB. Choose "Deferred" in the calculator to see yours.
USPS and other civil service employees
Postal Service employees hired into FERS use exactly the same formula, eligibility rules and MRA table as every other agency, so this calculator works for USPS careers too. If you were hired before 1984, you may be under the older Civil Service Retirement System (CSRS), which uses a different formula. Railroad workers are covered by the Railroad Retirement Board instead: see our railroad retirement calculator.
FERS cost-of-living adjustments (COLA)
FERS retirees get a smaller COLA than Social Security when inflation is above 2%. If the Social Security COLA is 2% or less, FERS gets the same; between 2% and 3%, FERS gets 2%; above 3%, FERS gets the Social Security figure minus one point.
| Effective | Social Security / CSRS | FERS |
|---|---|---|
| January 2026 | 2.8% | 2.0% |
| January 2027 | 3.6% | 2.6% |
Most regular FERS retirees get no COLA until they turn 62. Special provision and disability retirees are exceptions, and the FERS Supplement never gets one.
Is FERS retirement worth it?
FERS is designed as three pieces that work together: the annuity this calculator estimates, Social Security, and the Thrift Savings Plan, where your agency adds 1% automatically and matches up to another 4% when you put in 5%. The annuity alone is modest, about a third of your High-3 after 30 years. Combined with Social Security and a well-funded TSP, it's one of the stronger retirement packages available, especially with the inflation protection after 62. Use our TSP retirement calculator to see the third leg.
How do I find out how much my FERS retirement will be?
- Ask your agency's HR or benefits office for a retirement estimate. Many agencies also give employees an online benefits system that projects the annuity.
- Check your service computation date on your SF-50 and your sick leave balance on your Leave and Earnings Statement, then plug them in above.
- OPM's Federal Ballpark E$timate is a savings planner rather than an annuity calculator, so use it alongside this tool, not instead of it.
FERS retirement calculator in Excel or Google Sheets
Put High-3 in B1, years of service (including sick leave and military) in B2 and age at retirement in B3:
- Multiplier:
=IF(AND(B3>=62,B2>=20),1.1%,1%) - Basic annuity:
=B1*IF(AND(B3>=62,B2>=20),1.1%,1%)*B2 - MRA+10 reduction (months under 62 in B4):
=B4*5/12%
Remember that sick leave can't be used to reach eligibility, so check the eligibility table separately.
Planning the rest of your federal retirement
See how your TSP and annuity work together with the TSP calculator, estimate the tax on your annuity with the retirement tax calculator, check how long your savings will last with how long will my retirement savings last, and value your pension as a lump sum with the pension net worth calculator. Served in uniform before your civilian career? The military retirement calculator covers that pension.
Rules and figures come from the U.S. Office of Personnel Management: FERS eligibility, FERS computation, BAL 18-103 on sick leave and the 1.1% formula, service credit and military deposits and the CSRS/FERS Handbook chapter on the annuity supplement. 2027 COLA figures as reported by Federal News Network. This page gives planning estimates; your official annuity is calculated by OPM.
FERS retirement questions
What federal employees ask most before they retire.
How is FERS retirement calculated?
Multiply your High-3 average salary by your years of creditable service and by 1%. If you retire at 62 or older with at least 20 years, use 1.1% instead. Special provision employees use 1.7% for their first 20 years. Then subtract any MRA+10 reduction (5% for each year under 62) and the cost of any survivor benefit.
What is my FERS minimum retirement age (MRA)?
It depends on your birth year: 55 if born before 1948, rising by two months a year to 56 for births from 1953 to 1964, then rising again by two months a year to 57 for anyone born in 1970 or later.
How much is a FERS pension after 20 years?
With a $95,000 High-3, 20 years at 1% is $19,000 a year. If you are 62 or older when you retire, the 1.1% multiplier makes it $20,900 a year. Retiring at your MRA with 20 years and starting before 60 adds a 5%-a-year reduction until 62.
Does unused sick leave count toward FERS retirement?
Yes, for the amount but not for eligibility. Every 2,087 hours adds a year to the service used in your annuity formula, and OPM confirmed in BAL 18-103 that it also counts toward the 20 years needed for the 1.1% multiplier. It can't be used to reach the minimum service to retire or to raise your High-3.
Can I retire at 57 under FERS?
If your MRA is 57 (born 1970 or later), yes. With 30 years of service you get an unreduced annuity plus the FERS Supplement. With 10 to 29 years you can still retire, but the annuity is reduced 5% for each year you are under 62, unless you postpone the start date.
Who gets the FERS Supplement and how much is it?
Employees who retire before 62 on an immediate, unreduced annuity: MRA with 30 years, 60 with 20 years, or special provision. It equals your estimated Social Security at 62 times your FERS civilian years divided by 40, and it stops at 62. MRA+10 and deferred retirees don't receive it.
How much does a FERS survivor benefit cost?
A full survivor benefit, paying your spouse 50% of your annuity, reduces your annuity by 10%. A partial benefit of 25% costs 5%. Your spouse must consent in writing to anything less than the full benefit.
What is the best age to retire from federal service?
For many employees it is 62 with at least 20 years, because that unlocks the 1.1% multiplier. Retiring at your MRA with 30 years, or at 60 with 20, is the earliest point with no reduction and adds the FERS Supplement until 62. Retiring under MRA+10 without postponing is usually the most expensive choice.
Is the FERS COLA the same as Social Security's?
No. When inflation is above 2%, FERS retirees get less. For January 2027, Social Security and CSRS rise 3.6% while FERS rises 2.6%. Most regular FERS retirees don't get any COLA until they turn 62.
Is this the official OPM FERS calculator?
No. FinToolHub is independent and not affiliated with OPM. This calculator applies OPM's published FERS rules to give you a planning estimate. Your official annuity estimate comes from your agency's HR office, and OPM calculates the final amount when you retire.