Pensions · Updated for 2026
Railroad Retirement Calculator
Estimate your monthly railroad retirement annuity: Tier II from the Railroad Retirement Board formula, plus your Tier I, early-retirement reductions, the 60/30 rule and what your spouse can receive.
The short answer
Railroad retirement is two benefits added together. Tier I works like Social Security. Tier II is 0.7% of your average monthly railroad pay in your highest 60 months, times your years of service. With 30 years of service you can retire at 60 with no reduction; with fewer years the earliest age is 62, and retiring then can cut both tiers by up to 30%.
Estimate your railroad retirement annuity
Your Tier II then uses age 65 as full retirement age, so early retirement costs less.
Only if you have 25+ years, a current connection and some railroad service before October 1981.
50% of your Tier I and 45% of your Tier II, with spouse reductions and offsets.
Your estimated monthly annuity
$0
Per year
$0
This is a planning estimate using the RRB's published formulas and 2026 figures. Tier I is your input because it depends on your full earnings history; the RRB calculates the official amount when you apply. Pay above the 2026 Tier II cap of $11,425 a month is not counted.
How is railroad retirement calculated?
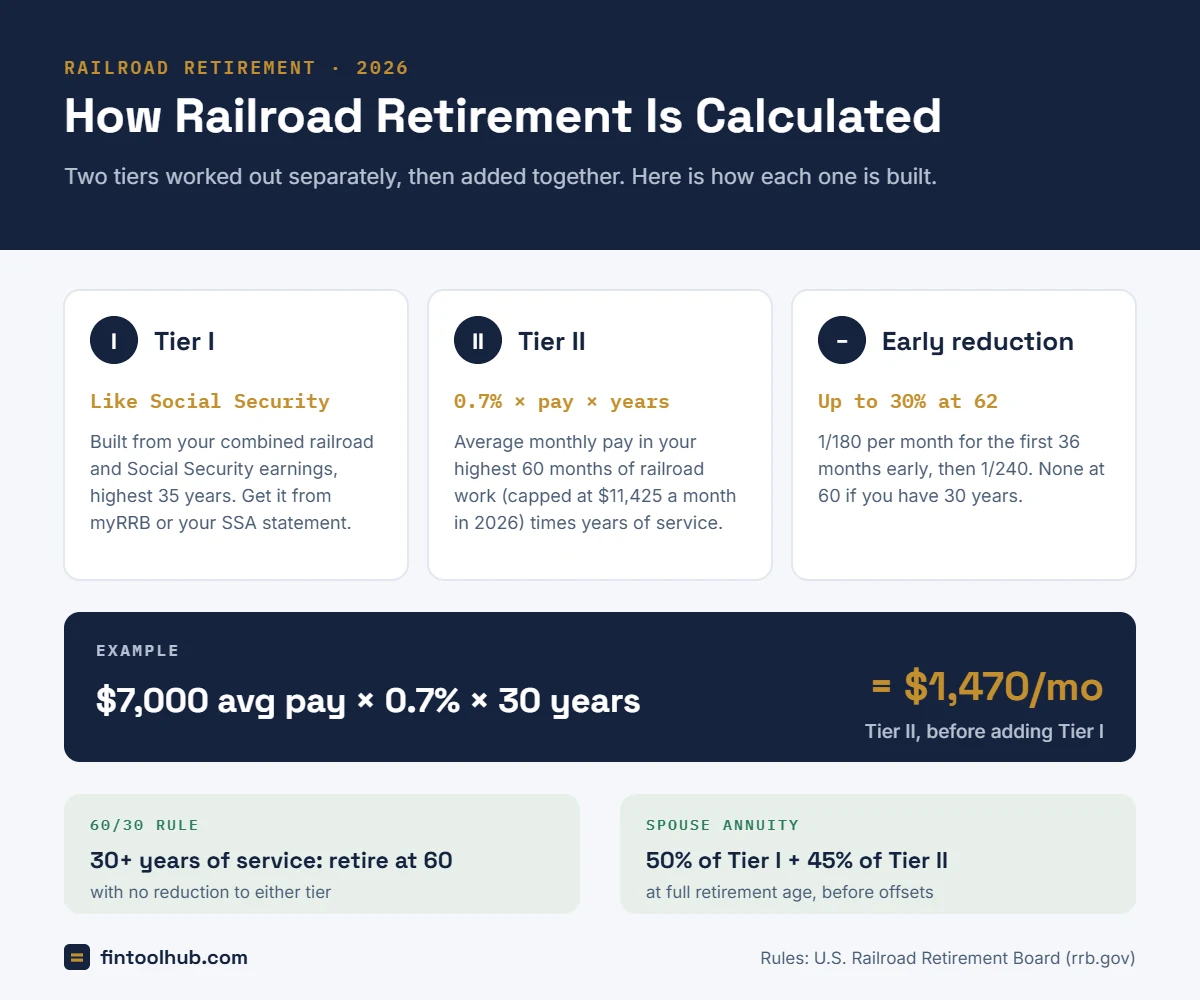
Railroad workers don't pay into Social Security on their railroad pay. They pay into the Railroad Retirement system instead, run by the U.S. Railroad Retirement Board (RRB), and it pays you in two layers.
- Tier I is worked out the same way as a Social Security benefit, using your railroad pay and any Social Security-covered work combined.
- Tier II is a separate, railroad-only pension on top of that, based on your railroad pay and years of service.
- If you retire before full retirement age without 30 years of service, each tier is reduced separately.
Add the two tiers together and you have your monthly annuity. That is exactly what the calculator above does.
Tier I: the part that works like Social Security
Tier I uses the same formula Social Security uses: your highest 35 years of earnings, indexed for wage growth, run through the year's bend points. Because it needs your whole earnings history, no quick calculator can work it out properly from a few numbers, and you should be wary of any tool that claims to.
The good news is that you don't have to calculate it. Log in to myRRB, the RRB's online account at rrb.gov, and request a retirement benefit estimate: it shows your Tier I. If you also worked outside the railroad, the RRB combines those Social Security earnings with your railroad pay, so the myRRB figure is the one to use. A Social Security statement on its own usually leaves out railroad pay and will understate Tier I.
Enter the full-retirement-age Tier I amount above and the calculator applies the right reduction for the age you plan to leave.
Tier II: 0.7% of your best five years of pay, for every year you worked
The 60 months are your highest-paid months, not simply your last five years, so a final year on reduced hours doesn't sink your pension. Pay only counts up to the Tier II earnings cap, which is $137,100 for 2026, or $11,425 a month.
A quick example: you averaged $7,000 a month in your best five years and worked 30 years. Your Tier II is $7,000 × 0.007 × 30 = $1,470 a month, before any reduction. Someone who maxed out the cap for 30 years would get $11,425 × 0.007 × 30 = $2,399.25.
How much railroad retirement will I get after 20, 25 or 30 years?
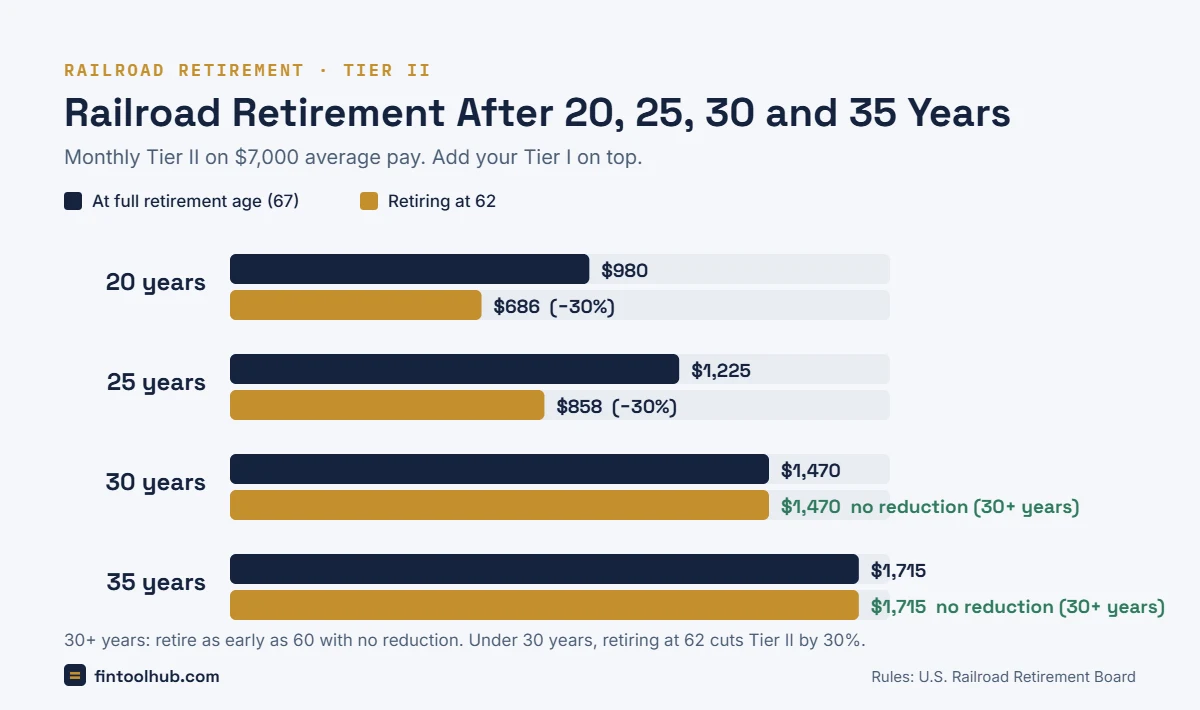
Years of service matter twice: they multiply your Tier II, and 30 of them unlock retirement at 60 with no reduction. Here is Tier II alone on $7,000 average monthly pay. Your Tier I comes on top.
| Years of service | Tier II at full retirement age | Tier II if you retire at 62 |
|---|---|---|
| 20 years | $980 | $686 (30% less) |
| 25 years | $1,225 | $858 (30% less) |
| 30 years | $1,470 | $1,470 (no reduction) |
| 35 years | $1,715 | $1,715 (no reduction) |
The jump between 25 and 30 years is bigger than it looks. At 62, the worker with 30 years keeps the full $1,470, while the worker with 25 years drops to about $858. If you're a few years short of 30, it is usually worth running both dates in the calculator before you put in your papers.
Can I retire at 60? The 60/30 rule
Yes, if you have 30 years of railroad service. You can retire as early as 60 with no reduction to either tier, which is the biggest advantage the railroad system has over Social Security.
If you hired out young, you may reach 30 years well before 60. Someone who started at 24 hits 30 years at 54, but still has to wait until 60 to draw the annuity. Without 30 years, the earliest you can retire is 62, with a reduction for each month you are under full retirement age.
Retiring before full retirement age
If you have fewer than 30 years, both tiers are reduced for each month you start before your full retirement age:
- 1/180 per month (about 0.56%) for the first 36 months, roughly 6.7% a year
- 1/240 per month (about 0.42%) for any months beyond that, 5% a year
With a full retirement age of 67, retiring at 62 is 60 months early: 36 months × 1/180 (20%) plus 24 months × 1/240 (10%) is a 30% reduction.
| Year of birth | Full retirement age |
|---|---|
| 1943–1954 | 66 |
| 1955 | 66 and 2 months |
| 1956 | 66 and 4 months |
| 1957 | 66 and 6 months |
| 1958 | 66 and 8 months |
| 1959 | 66 and 10 months |
| 1960 or later | 67 |
The 1983 exception: if you had railroad service before August 12, 1983, your Tier II uses 65 as its full retirement age, so the Tier II cut at 62 is capped at 20% instead of 30%. The RRB's own example shows the difference: a $1,200 Tier II becomes $960 instead of $840.
What will my spouse get from railroad retirement?
A spouse annuity is worked out from your benefit, not your spouse's work record. Before any reductions it is 50% of your unreduced Tier I plus 45% of your unreduced Tier II.
- When it can start: at 62, or at 60 if you qualify under the 60/30 rule. Your own annuity has to have started first.
- Early reduction: starting before the spouse's full retirement age cuts the spouse Tier I by 1/144 per month for the first 36 months, up to 35% at 62. Under the 60/30 rule, a spouse who is 60 or older has no reduction.
- Social Security offset: if your spouse has a Social Security benefit of their own, it reduces the spouse Tier I. It does not touch the spouse Tier II.
The RRB gives this example: an employee with $1,600 of Tier I and $1,200 of Tier II who retires under the 60/30 rule. A spouse who is 60 gets $800 of Tier I (50% of $1,600) and $540 of Tier II (45% of $1,200), before any offsets. Turn on the spouse option in the calculator to run your own numbers.
How much will railroad retirement go up in 2026 and 2027?
Tier I rises by the same cost-of-living adjustment (COLA) as Social Security. Tier II rises by 32.5% of that figure.
| Effective | Tier I increase | Tier II increase |
|---|---|---|
| January 2026 | 2.8% | 0.9% |
| January 2027 | 3.6% | 1.2% |
Supplemental annuities and vested dual benefits don't get these increases.
What is the average railroad retirement pension?
According to the RRB, the average regular annuity for a retired railroad employee will be $3,761 a month after the January 2027 increase, up $106. Employee-and-spouse couples will average $5,407 a month, and aged widow(er)s about $2,218. These are averages across everyone on the rolls, including short careers, so a 30-year employee with good pay usually receives more.
Who qualifies for railroad retirement?
You need at least 10 years (120 months) of railroad service, or 5 years (60 months) if all of that service was after 1995. The supplemental annuity and RRB survivor benefits also require a current connection with the railroad industry, which usually means 12 months of railroad work in the 30 months before your annuity starts.
The supplemental annuity
Some long-service employees get a small extra annuity from the railroad. It requires 25 or more years of service, a current connection and at least one month of railroad service before October 1981. It starts at 65, or at 60 with 30 years, and pays $23 a month plus $4 for each year over 25, up to $43 a month at 30 years. A private railroad pension can reduce it.
Is railroad retirement taxable?
Partly. Tier I is taxed like Social Security, so between 0% and 85% of it is taxable depending on your other income. Tier II is taxed like a private pension. To see what you would actually owe on both tiers alongside your other income, use our retirement tax calculator.
How to get your official estimate from the RRB
Use this calculator to explore your options, then confirm the numbers with the Railroad Retirement Board before you set a date:
- Create or log in to a myRRB account at rrb.gov and request a retirement benefit estimate.
- Check your record of service months and earnings. Missing months are the most common reason an estimate comes out lower than expected.
- Call the RRB on (877) 772-5772 or visit a field office if anything looks wrong. It is far easier to fix before you retire than after.
Working it out in Excel or Google Sheets
If you'd like to keep your own copy, three cells do most of the work. Put average monthly pay in B1, years of service in B2 and Tier I in B3:
- Tier II:
=0.007*MIN(B1,11425)*B2 - Reduction for months early (in B4):
=MIN(B4,36)/180+MAX(B4-36,0)/240 - Monthly annuity:
=(B3+0.007*MIN(B1,11425)*B2)*(1-reduction)
Leave the reduction at zero if you will have 30 years of service and are at least 60.
Planning the rest of your retirement
Your annuity is one piece of the plan. To see what your railroad pension is worth as a lump sum on your balance sheet, try the pension net worth calculator. To check how long your savings will last alongside the annuity, use how long will my retirement savings last. To count down to your date, there's the days to retirement calculator. If you are a federal employee rather than a railroad employee, your pension is FERS: see the FERS retirement calculator.
Rules and figures in this guide come from the U.S. Railroad Retirement Board: age reductions, spouse and divorced spouse annuities, January 2027 cost-of-living increase and 2026 earnings bases. This page gives planning estimates; your official annuity is calculated by the RRB.
Railroad retirement questions
The questions railroaders ask most before they retire.
How do you calculate railroad retirement?
Add two amounts. Tier I is calculated like Social Security from your combined railroad and Social Security earnings. Tier II is 0.7% of your average monthly railroad pay in your highest 60 months, times your years of service. If you retire before full retirement age with fewer than 30 years of service, each tier is reduced by 1/180 per month for the first 36 months early and 1/240 per month after that.
How much railroad retirement will I get after 20 years?
With 20 years, Tier II is 14% of your average monthly pay in your best 60 months: about $980 a month on $7,000 of pay. Tier I comes on top. If you retire at 62 with a full retirement age of 67, both tiers are reduced by 30%, so that Tier II becomes about $686 a month.
What is the average pension for a railroad worker?
The Railroad Retirement Board says the average regular annuity for a retired railroad employee will be $3,761 a month after the January 2027 increase. Employee-and-spouse couples will average $5,407 a month.
How much will railroad retirement go up in 2026?
In January 2026, Tier I rose 2.8% and Tier II rose 0.9%. In January 2027, Tier I rises 3.6% and Tier II rises 1.2%. Tier II always rises by 32.5% of the Social Security cost-of-living adjustment.
Can I retire from the railroad at 60?
Yes, if you have 30 years of railroad service. Under the 60/30 rule you can retire at 60 with no reduction to either tier. With fewer than 30 years, the earliest age is 62, with a reduction for each month before your full retirement age.
How many months are used to calculate railroad retirement?
Tier II averages your highest 60 months of railroad pay, which do not have to be your last 60, and only counts pay up to the Tier II earnings cap ($11,425 a month in 2026). Tier I uses your highest 35 years of earnings, the same way Social Security does.
How much does a spouse get from railroad retirement?
Before reductions, a spouse annuity is 50% of the employee's Tier I plus 45% of the employee's Tier II. It can start at 62, or at 60 with no reduction if the employee qualifies under the 60/30 rule. A Social Security benefit the spouse earned on their own work reduces the spouse Tier I but not the Tier II.
Do I get Social Security on top of railroad retirement?
Not twice for the same work. Tier I already counts any Social Security-covered earnings you have. If you are also entitled to a separate Social Security benefit, your Tier I is reduced by that amount, and the RRB usually pays the combined benefit.
Is railroad retirement taxable?
Partly. Tier I is taxed like Social Security, so 0% to 85% of it can be taxable depending on your other income. Tier II is taxed like a private pension.
Is this the official RRB calculator?
No. FinToolHub is independent and not affiliated with the Railroad Retirement Board. This calculator uses the RRB's published formulas to give you a planning estimate. Your official figure comes from your myRRB account or an RRB field office.